Say ‘yes’ more.
Our behavioural interventions transform risk profiles.
A new lens for credit risk, and a personalised financial coach to turn rejected borrowers into credit-ready customers.
Last year we wrote off in excess of £80m.
£80m is a lot of customers who have found themselves at the receiving end of a lot of communications and stress from us… there are human stories behind that, as well as a commercial one for us.
Our lenses support safe lending
The only solution in the market that is proven to improve financial performance for safe financial inclusion.
Open Banking Intelligence™
Surface hidden prime customers that credit scores miss.
7% accuracy uplift vs CRA score alone
Psychometrics
Our Readiness Score™ reveals borrower mindset and intent.
36% of financial health explained by psychometrics
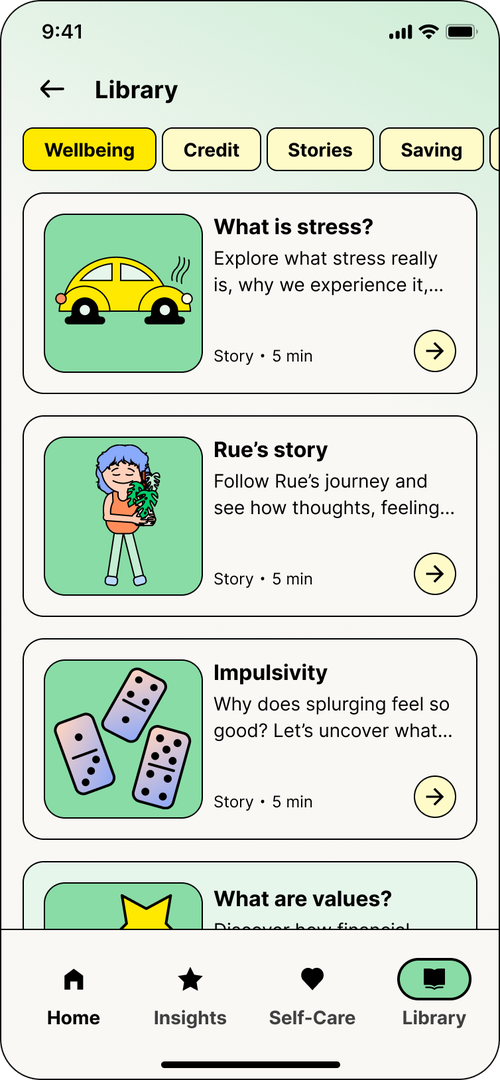
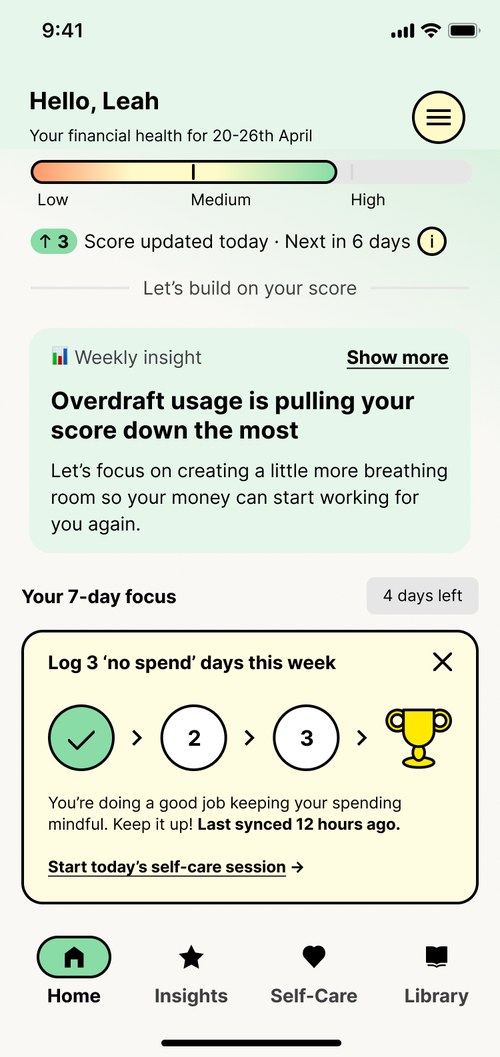
Good With app
Transform financial health with our FinIQ™ interventions.
15% improvement from regular app usage
Open Banking Intelligence™
Surface hidden prime customers that credit scores miss.
Our 45+ financial behaviour indicators reveal spending patterns, risk trajectories, and vulnerability markers, helping acquisition teams safely increase approvals.
Use our OB provider, or connect your existing one, to reveal the “hidden good” customers using our secure interactive portal.
+7% accuracy
in default prediction over baseline credit scorecards.
40% ‘low-risk’ declines
identified as potential accepts based on our credit risk score.
Readiness Score™
Add our psychometric layer onto Open Banking to reveal a person’s financial mindset and behaviour.
Our Readiness ScoreTM and behavioural profiling reveals the likely trajectory of an individual. Enabling you to make fairer, safer lending decisions, and determine the most appropriate intervention for customers.
Applicants run through a 5 minute psychometric quiz, with 96% average completion rates.
36% of financial health
explained by psychometrics, giving you an extra lens.
FinIQ™
Turn rejected borrowers into credit-ready customers.
Transform financial health with hyper-personalised interventions in our financial coaching app, FinIQ™.
Build money confidence and reduce impulsivity across your customer base, and retain declines on a guided pathway until they’re ready for credit.
+15% improvement
in Readiness Score™ with regular app usage over 1-2 months.
For people who have struggled to manage their finances properly, a poor credit score can make it very difficult to get support for their next financial step.
Your approach is much more than just financial support—it is an excellent form of financial education that helps people learn, improve, and move forward with confidence.
Start with an app referral programme
FinIQ™ turns ‘No’ into ‘Yes’.
Transform financial health across your customer base and prove to regulators that you are actively supporting vulnerable individuals.
No integration needed. Customers download and use the app, lenders preview Open Banking Intelligence™ and Readiness Score™ insights.
Scientific rigour
Multidisciplinary and credentialed team who understand people and people data.
-
Gabriela Isas
Founder & CEO
-
Dr. Ellie Kallis
Co-founder & Chief Scientific Officer
-
Dr. Victoria Root
Behavioural Science Lead
-
Dr. Rory Spanton
Senior Behavioural Data Scientist
-
Elisabeth Carr
Senior Full Stack Software Developer
-
Emily Blackburn
Customer Success Manager
-
Paula Kaminska
Senior UX and Service Design Strategist
Investor Advisory board of credit and fintech domain experts:
The future of financial inclusion is here
What would Good With behavioural models reveal in your customer base?
Request a retrospective view on the low-risk rescues within your decline dataset. Understand the potential to transform risk profiles across your customer base.
Supported by:
¹ Based on probability of default modeling across 5,000+ loan applications with a community lender (February 2026).
² Analysis of Readiness Score™ model performance; psychometric indicators accounted for 36% of the model’s ability to explain variance in financial data outcomes (December 2025).
³ Average Readiness Score™ increase observed in the most highly engaged Good With app users (completed ≥ 16 lessons) over a 1–2 month period across diverse lender demographics (September 2026).
⁴ Based on a credit union pilot, analysing 40 declined applications with accessible Open Banking data; the model identified 16 individuals (40%) as low-risk, indicating safe lending expansion potential (May 2026).